BEST Phoenix Property Management Company Near You in Gilbert, AZ
Home Ladder Property Management helps Arizona landlords buy, sell, rent, manage, repair, and renovate rental properties in/near Phoenix, AZ.
Work With the Best Locally-Owned Property Management Company in Phoenix
At Home Ladder Property Management, we bridge the gap between owning a property and running a successful real estate business. An experienced leader in the Phoenix market, recognized as a Top 100 U.S. property management company in 2025, ranked #1 in the Phoenix-Mesa-Chandler area, and voted the Best Property Management Company in Gilbert for 2025 by BusinessRate. Home Ladder provides specialized property management services for both single-family homes and multifamily properties. Whether you are an investor looking to maximize returns with turnkey portfolio growth or a landlord seeking affordable, efficient oversight to protect your assets, our team is here to monitor your investments and deliver consistent performance. Get a free property analysis today and discover how easy it can be to enjoy stress-free ownership.
Located in Gilbert, AZ. Valleywide Service.
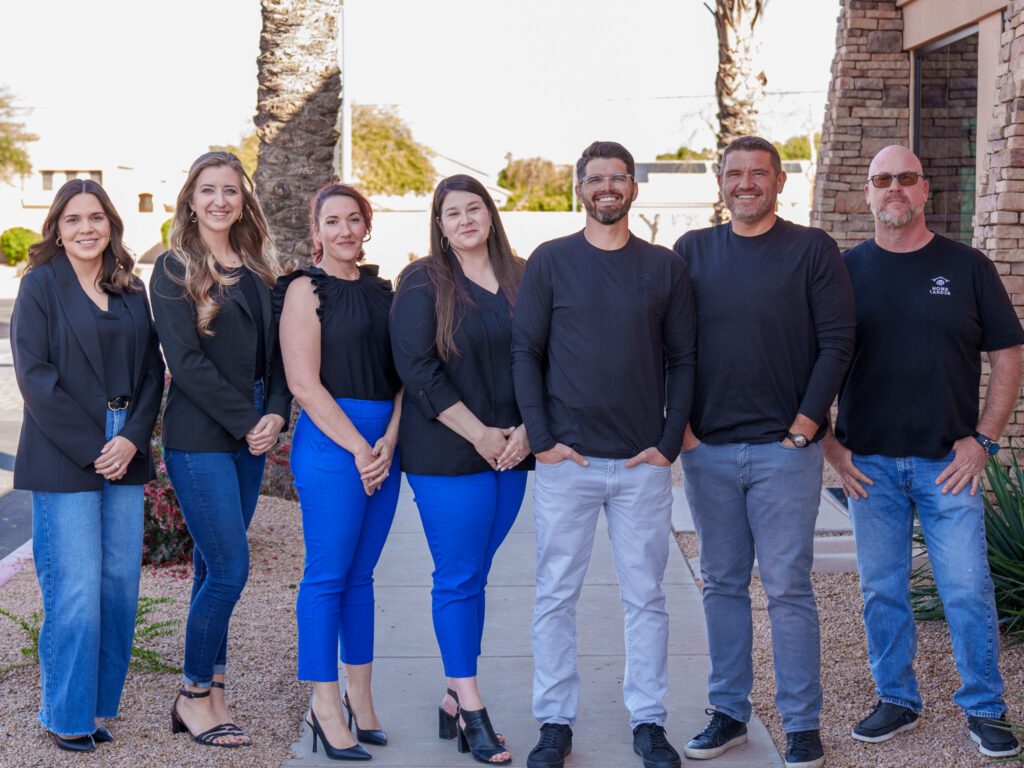
Meet Team Home Ladder Property Management
Top Locally-Owned Phoenix Property Management Company
Founded in Gilbert, AZ, Home Ladder provides reliable, comprehensive real estate investment support across the Phoenix metro. We help landlords maximize returns, protect their assets, and enjoy stress-free ownership. From single homes to large property portfolios, we make Arizona property ownership simple and profitable with full-service property management near you.
Property Management
Search Homes For Rent
Why Phoenix Real Estate Investors Partner With Home Ladder as Their Rental Property Management Company
Stress Less
24-hour maintenance coverage
Avoid bad tenants like Chaos and Disorder
99% lease fulfillment rate
Local, licensed, expert property managers
Preventative maintenance team
Save Time
Financial reporting at your fingertips
No leasing calls
No negotiating with vendors
No trips to the property
Proactive management
Earn More
Competitive local vendor network
Average vacancy rate < 14 days
Buy/Sell services from a trusted advisor
Off-market deals = instant equity
3.5-year average tenancy
Home Ladder’s Comprehensive Rental Property Management Process
We don’t just collect rent; we screen your renters to find the best candidates. Our proven evaluation process is designed to attract high-quality residents, achieving a 99.4% rent collection rate. Every rental application undergoes a rigorous review, including credit checks, income verification, criminal background checks, and eviction history, ensuring we only place the most reliable tenants.
Once a tenant is selected, we document the property’s status with a detailed move-in checklist and professional photography. This ensures we can accurately negotiate any necessary security deposit dispositions at the end of a lease term.
Proactive Care and Communication
At Home Ladder, we proactively maintain the value of your investment. And through our owner portal, we communicate vital updates and provide real-time financial reporting. We believe that transparency is the key to a successful partnership. Our team will:
Advertise your property across 40+ listing platforms to shorten vacancy times.
Inspect your investment annually. Proactive property inspection can catch small issues before they become costly repairs.
Coordinate with our network of vetted vendors to provide commercial-grade maintenance at fair prices.
Enforce lease terms strictly and professionally to protect your interests.
Expert Handling of Legalities
The Arizona rental market requires a manager who can negotiate complex situations with ease. From managing security deposit disputes to navigating the legal eviction process if a tenant stops paying, we handle the tough conversations so you don’t have to. If an eviction becomes necessary, we work with local legal experts to evict non-compliant residents quickly and legally, protecting your bottom line.
Whether you own a small single-family rental or a large multifamily complex, Home Ladder offers the specialized expertise needed to thrive in Phoenix. Partner with the best property management company in Phoenix and start experiencing a more efficient, stress-free way to grow your wealth.
Ready to climb higher? Contact Home Ladder today for a free rental analysis.
Arizona Real Estate Experience & Results
99.4%
Rent Collection Rate
50+
Years of Experience
35+
Communities Served in AZ
27.8%
Average Repair Savings
5-Star
Google Rating
Save time, earn more, and reduce stress with our local team and proven processes.
Let’s talk about your long-term goals.
Is Our Phoenix Rental Management Company a Good Fit?

Do you believe a clean and safe home attracts quality tenants?
Do you believe providing quality housing improves your community?
Do you believe real estate is a long-term investment that can provide generational wealth and financial freedom?
Do you want a local professional to oversee your rental properties, resolve problems and be your dedicated point of contact?
Do you desire to build a long-term relationship based on big ambitions, tempered by patience, prudence, and integrity?
If you answered "yes"...
What Our Phoenix Residential Property Management Clients Are Saying About Us


Areas We Serve
Our residential property management company serves the greater Phoenix area, including:
Anthem
Carefree
Laveen
Paradise Valley
Sun City
Sun City West
Youngtown
Ready to Discuss Your Long-Term Real Estate Investment Goals?
Types of Properties & Services
Rental Property Management
Apartment Property Management
Condo Property Management
Turnkey Property Management
Residential Property Management
(Home Rental Property Management)
Investment Property Management
Licensed Property Managers
Single-Family Rental Property Management
Property Maintenance
Helpful Phoenix Property Management Resources:

Tip: Home Ladder has no hidden costs or fees.

Phoenix Metro, Arizona Real Estate and Rental Market Update
September 2026
Sales Lose Momentum as Rentals Enter Fall on Firmer Ground
The Phoenix Metro housing market continued to tell two different stories in September, but the sales side took a turn.
August’s signs of stabilization gave way to rising inventory and weaker contract activity. Buyers had more homes to choose from just as higher mortgage rates reduced what they could afford. Closing prices held relatively steady, but the conditions behind those closings became less favorable for sellers.
The rental market remained stronger than a year ago. Available listings were substantially lower, rents were higher, and homes leased faster than last September. However, a small increase in inventory and a monthly decline in rents suggest owners should prepare for a more competitive fall leasing season.
The differences between cities also became harder to ignore. Chandler’s rental market looked very different from Peoria’s. Scottsdale retained more sales leverage than most of the Valley, while Tempe showed that an established location does not guarantee a strong market.
Sales Market Highlights
Active Listings: 21,895 — up 8.1% from August and approximately 4.0% year over year
Median Sold Price: $250.75 per SF — up 0.6% monthly and down approximately 0.3% year over year
Average Days on Market: 62 days — compared with 63 in August and 65 last September
30-Year Mortgage Rate: 7.28% in Freddie Mac’s October 1 weekly reading
The mortgage figure is an early-October weekly reading, not September’s monthly average.
September added 1,639 active sales listings across Maricopa and Pinal counties. That reversed the inventory declines seen through much of the summer.
Some increase is expected when sellers return after summer. The concern is the combination of more supply and less buying activity.
Across the broader regional market, listings under contract declined 10.2% from August and were 11.2% below a year earlier. This was the largest September decline in under-contract listings since 2022.
This is a meaningful change from August’s more encouraging demand signals. Sellers entered fall facing more competing homes and a smaller pool of committed buyers.
Why Stable Closing Prices Can Hide a Weakening Market
September’s median sold price per square foot rose slightly, and average marketing time improved by one day. Those results might suggest the market was strengthening.
The timing of the data explains the disconnect.
Many September closings came from agreements negotiated in July or August. They reflect decisions made before buyers experienced the full impact of September’s higher financing costs.
Pending and under-contract listings offer an earlier indication of future closings. When those measures fall while active inventory rises, pressure can build before it becomes obvious in completed-sale prices.
The mix of homes selling also matters. A larger share of higher-priced properties can support a metro price statistic even while individual sellers become more flexible.
For sellers, recent comparable sales remain useful, but they need to be evaluated alongside today’s active competition and buyer response. A successful closing from two months ago does not guarantee the same negotiating position today.
Mortgage Costs Are Making Builder Competition More Important
Freddie Mac’s 30-year mortgage benchmark reached 7.28% in its October 1 release, up from 7.03% the previous week. Higher borrowing costs make buyers more sensitive to monthly payments, even when asking prices barely change.
That gives financing incentives greater importance.
A resale home may compete with a builder offering closing-cost assistance or a mortgage-rate buydown. Comparing listing prices alone can miss a meaningful difference in the buyer’s upfront costs or payment.
Nationally, NAHB reported that 66% of builders used sales incentives in September and 38% cut prices. Those are national figures, but they illustrate the competitive tools available to builders.
In communities with substantial nearby new-home choices, sellers should compare the complete competing offer: price, condition, financing terms and incentives.
September’s Maricopa County affidavit statistics also showed new-home closings down 15.6% year over year. Builders are competing for buyers in a constrained market too.
The Sales Divide Extends Beyond Established Cities Versus Outer Suburbs
At the beginning of October, Scottsdale and Chandler remained in seller-favorable territory. Buckeye, Maricopa, San Tan Valley and Surprise remained buyer-favorable.
However, the shift toward buyers extended across all 18 major cities tracked in the regional market comparison over the preceding month. Even stronger markets lost some negotiating power.
September’s city-level results show why broad labels need qualification:
Scottsdale’s median sold price per square foot was $428.44, up 4.1% year over year, although average marketing time remained a relatively long 77 days.
Chandler homes sold in an average of 49 days, faster than the metro’s 62, while its median sold price per square foot was below last year.
Gilbert’s median sold price per square foot increased year over year, but active sales listings were also substantially higher.
Tempe had rising sales inventory and a lower median sold price per square foot, despite its established location.
These measures describe different aspects of market strength. Faster sales do not automatically mean rising prices, and stronger prices do not guarantee a quick sale.
The practical question is how much competition exists for a particular home at its price point, not simply whether its city is considered desirable.
Rental Market Highlights
Active Rental Listings: 4,999 — up 2.2% from August and down approximately 18.1% year over year
Median Rent: $1.37 per SF — down 1.4% monthly and up 3.0% year over year
Median Days on Market: 33 days — unchanged from August and down from 40 last September
Compared with September 2025, rental owners faced 1,108 fewer competing active listings across the metro.
That improvement helps explain why homes leased faster and the median rented price per square foot remained above last year. It gives owners a better starting position than they had entering the previous fall.
But September’s monthly direction was less favorable. Inventory increased slightly, and the median rented price per square foot slipped from August’s $1.39.
Both trends can be true: the market can improve year over year while cooling seasonally.
The 3.0% annual increase also should not be treated as a recommended rent increase for every property. It describes the median of homes that leased, with changes in property size, location and quality affecting the result.
Likewise, fewer active listings do not directly measure the vacancy rate across all rental homes or apartment communities.
Which Rental Markets Are Outperforming the Metro?
Chandler and Gilbert showed some of the clearest advantages in leasing speed.
Chandler’s median rental marketing time was 24 days, nine days faster than the metro. Its median rent reached $1.50 per square foot, with annual growth exceeding the metro’s 3.0%.
Gilbert leased in a median of 25 days. Its $1.33 per square foot was below the metro figure, yet homes moved considerably faster. That is a useful reminder that achieving a higher rent per square foot and finding a tenant quickly are different measures.
Phoenix was also relatively steady, with 31-day median leasing time and $1.49 per square foot.
Buckeye and San Tan Valley offer another important contrast. Their sales markets remained buyer-favorable, while rentals leased in medians of 28 and 29 days—both faster than the metro.
Weak buying activity does not automatically translate into weak rental demand. Financing costs can keep households renting longer, although listing statistics alone cannot quantify how many renters postponed a purchase.
Where Rental Owners Need More Caution
Peoria’s September results were a notable change from August.
Its median rental marketing time increased from 30 to 44 days, while median rent declined from $1.26 to $1.19 per square foot. Active listings fell during the same period.
That combination shows why lower inventory alone is insufficient evidence of a stronger market. Demand, pricing and the mix of available homes also matter.
Tempe remained slower than the metro at 47 days, with median rent of $1.55 per square foot—below last year. Its higher rent per square foot did not translate into faster leasing.
Maricopa had 122 active rentals, versus 81 last September, moving in the opposite direction from the metro’s annual inventory decline. Its median leasing time improved from August but remained slower than a year earlier.
Casa Grande and Coolidge also recorded lower rents per square foot than last September. Coolidge’s relatively quick 27-day median suggests homes can still lease promptly at the prices renters are accepting.
For owners, the lesson is to evaluate inventory, achieved rents and leasing speed together. Any one statistic can give an incomplete picture.
Rental Construction Is Slowing, but Existing Competition Still Matters
Northmarq’s second-quarter Phoenix build-to-rent report, published in September, described a sharp slowdown in new deliveries.
Developers completed more than 5,000 units annually on average from 2023 through 2025, compared with fewer than 1,400 in the first half of 2026. A smaller construction pipeline could give existing communities more time to fill vacancies.
The outlook differs locally. Northmarq identified continued pipeline pressure in Buckeye, while recent supply waves in San Tan Valley and Queen Creek had already been delivered.
Delivered does not necessarily mean fully leased. Existing communities can continue competing for residents even after construction ends.
For an individual landlord, the relevant question is what comparable homes are available nearby, including concessions that reduce a renter’s effective cost.
Our earlier coverage of Pinal County’s multifamily development pipeline provides background on that competition. Its historical project counts should not be treated as September inventory.
What Last Winter Suggests About the Months Ahead
Last winter provides a useful reference for rental owners.
Between September 2025 and January 2026, the metro’s median rented price per square foot declined from $1.33 to $1.28. Median days on market increased from 40 to 47.
Active rental listings fell over that period, too.
The market became slower even with fewer listed alternatives. That is why owners should not assume September’s lower annual inventory will protect them from winter leasing pressure.
This year’s starting position is stronger: higher rents, fewer listings and faster leasing than last September. That could cushion seasonal weakness, but it does not eliminate it.
Owners approaching a vacancy should monitor inquiries, showings and qualified applications early. Waiting several weeks to respond to weak interest can turn a modest pricing adjustment into a larger vacancy expense.
For illustration, a vacant month at $2,400 represents the same gross revenue as $200 per month over a full year. The best asking rent is the one that supports the strongest realistic revenue outcome, including time vacant.
Population Growth Supports Demand, but Timing Still Matters
Our earlier review of Phoenix’s population growth highlighted continued growth in 2025 despite a slower pace.
That supports the long-term need for housing. It does not ensure every new community or individual rental fills immediately.
New residents, available housing, employment and household budgets do not align evenly across the Valley. A growing metro can still have neighborhoods where supply temporarily exceeds demand at the asking price.
For investors, long-term confidence in Phoenix needs to be paired with realistic near-term rent, vacancy and maintenance assumptions.
Key Takeaways
September reversed August’s sales inventory improvement, with active listings rising 8.1% monthly.
Falling contract activity is a more cautionary signal than the modest improvement in completed-sale prices.
Higher mortgage costs increase the importance of price, concessions and competing builder offers.
Scottsdale and Chandler retained relative sales strength, but even stronger markets moved toward buyers.
Rental conditions remained healthier than last September, with fewer listings and faster leasing.
Chandler and Gilbert outperformed the metro on rental speed; Peoria, Tempe and Maricopa warrant closer attention.
Slower construction could ease future supply pressure, but completed communities still compete for residents.
Fall and winter pricing should reflect local renter response, not a blanket assumption that lower inventory guarantees higher rents.
Overall Outlook
September’s sales data points toward a more challenging finish to the year for sellers if financing costs remain elevated. Rising inventory and fewer contracts suggest continued negotiation pressure, even if headline closing prices remain fairly steady.
Rentals enter fall in a better position than last year, but September’s monthly cooling argues for measured expectations. Owners should budget for seasonal changes in leasing speed and avoid projecting summer pricing into winter without checking current competition.
The market ultimately determines what buyers and renters will pay. Owners and their agents control the asking price, presentation and response to feedback.
For a specific property, those decisions should be grounded in nearby alternatives, condition, total housing cost and the owner’s financial goals.
If you own a rental in the Phoenix Metro, Home Ladder Property Management can provide a free rental analysis to help you compare your property with today’s competition and plan your next move.
August 2026
The Phoenix Metro housing market continues to tell two very different stories.
The sales market has stabilized, but buyers still hold meaningful leverage. Inventory is no longer rising rapidly, yet home prices remain slightly below last year as mortgage rates approach 7%.
The rental market looks considerably healthier. Available rental inventory is roughly 20% lower than last year, rents have returned to modest growth, and homes are still leasing faster than they did in August 2025.
The bigger story, however, is increasingly happening below the metro average. Scottsdale and Chandler look very different from Buckeye, Maricopa, and San Tan Valley—and new construction helps explain why.
Sales Market Highlights
Active Listings: 20,256 — down 0.6% year over year
Median Sold Price: $249.28 per SF — down approximately 0.4%
Average Days on Market: 63 days — down approximately 3.1%
30-Year Mortgage Rate: 6.87%
Phoenix’s sales market has stopped deteriorating, but it has not meaningfully recovered.
One year ago, active inventory was still 24.5% higher than the year before. Today, inventory is essentially flat. The surge in available homes that defined much of 2025 has largely worked its way through the market.
Normally, falling inventory would create stronger pricing pressure.
That isn’t happening.
The median sold price per square foot slipped again in August and remains slightly below last year. Mortgage rates rising to 6.87% continue to limit what buyers can afford, leaving sellers with less pricing power despite more balanced inventory.
The result is a relatively stable but buyer-friendly market—not a distressed one.
New Construction Is Widening the Gap Between Submarkets
The metro average also hides an important source of competition: new construction.
Resale inventory reported through ARMLS does not include every new home buyers can choose from. That matters most in fast-growing outer-ring communities.
Buckeye, Maricopa, San Tan Valley, Surprise, Apache Junction, and Coolidge continue to experience significant single-family development. In those markets, a resale seller may be competing against a builder offering a brand-new home, closing-cost assistance, or a mortgage-rate buydown.
That helps explain why some outer Valley markets remain weak even when resale inventory is declining.
By contrast, mature markets such as Chandler, Scottsdale, Gilbert, and Mesa have far less new single-family construction competing with existing homeowners.
This divide is likely to remain important as Arizona continues looking for ways to make new housing easier to build. We recently covered Arizona’s HB 2999 and its effort to reduce infrastructure costs for new communities.
The West Valley is also preparing for significant long-term growth. The Loop 303 extension now underway in Goodyear will improve access to future employment and housing areas stretching toward Buckeye and the southwest Valley.
More construction is good for long-term housing availability—but in the near term, it creates additional competition for resale homeowners.
Rental Market Highlights
Active Rental Listings: 4,891 — down approximately 20.3% year over year
Median Rent: $1.39 per SF — up 0.7%
Median Days on Market: 33 days — down 5.7%
The rental market has undergone a much more dramatic change.
In August 2025, rental inventory was 17.6% higher than the previous year.
Today, it is roughly 20% lower.
That represents a major swing in landlord competition.
Rent growth remains modest, but the direction has changed. Rents declined year over year through much of 2025 and early 2026 before stabilizing this summer. August’s $1.39 per square foot is the highest metro reading since spring 2025.
The market is tightening—but it is not overheating.
Median rental DOM increased from 28 days in July to 33 days in August as the summer leasing season ended. That seasonal slowdown is normal, and homes are still leasing faster than they did last August.
For landlords, the more important question this fall will be whether rental inventory remains substantially below 2025 levels.
Not Every Rental Market Is Strengthening Equally
The same geographic divide exists on the rental side.
Scottsdale, San Tan Valley, Peoria, Phoenix, Gilbert, and Mesa currently show some of the strongest rental fundamentals, generally combining lower inventory with healthier rent or leasing trends.
Tempe, Casa Grande, and Maricopa are more challenging.
New multifamily construction adds another layer.
Mesa, Peoria, Phoenix, Tempe, and San Tan Valley all have meaningful apartment or multifamily supply in the pipeline. That means today’s tight rental conditions should not automatically be projected several years into the future.
Other markets are moving the opposite direction. Multifamily permitting has slowed considerably in areas including Surprise, Gilbert, and Scottsdale, potentially creating a more favorable future supply environment for existing landlords.
Pinal County provides a good example of why investors need to watch both current inventory and future construction. We previously examined the county’s rapid multifamily development pipeline and what it could mean for Arizona rental investors.
Population Growth Still Supports Long-Term Housing Demand
Phoenix’s current weakness should also be viewed in a longer-term context.
The Valley continues adding residents even though population growth has slowed from its post-pandemic pace.
We recently looked at how Phoenix population growth continues to outperform most major U.S. metros.
That matters because today’s weak homebuying activity does not necessarily mean weak underlying demand for housing.
People still need somewhere to live.
At mortgage rates approaching 7%, some households that might otherwise purchase a home are remaining renters longer. That helps explain why the sales market can remain soft at the same time rental inventory is tightening.
Key Takeaways
Phoenix Metro sales inventory has largely stabilized after the large increases of 2025.
Home prices remain slightly negative despite lower inventory, showing that buyer demand remains constrained.
Mortgage rates near 7% continue to be the biggest obstacle to a stronger sales recovery.
New construction is adding significant resale competition in Buckeye, Maricopa, San Tan Valley, Surprise, and other fast-growing exurbs.
Scottsdale and Chandler remain among the strongest sales markets because of stronger demand and relatively limited new-home competition.
Rental inventory is roughly 20% below last year, a dramatic reversal from 2025.
Rents have stabilized and returned to modest positive growth.
August’s increase in rental DOM appears consistent with the normal end of the summer leasing season.
Multifamily construction means rental conditions vary significantly by submarket and may change as new projects are delivered.
Overall Outlook
Phoenix is not experiencing one housing market.
It is experiencing several.
The luxury and established portions of the Valley continue to outperform, while builder-heavy West Valley and Pinal County markets remain much more favorable to buyers.
On the rental side, significantly lower inventory has created healthier conditions for landlords, but rent growth remains modest and leasing activity should slow seasonally through the fall.
The simplest way to describe the Phoenix housing market today is:
Weak demand to buy does not mean weak demand for housing.
Unless mortgage rates decline significantly, we expect the sales market to remain relatively flat and buyer-friendly through the near term.
Rental fundamentals should remain stronger than sales fundamentals, particularly if available inventory stays well below last year’s levels.
For rental owners, that makes accurate pricing increasingly important. The Valley-wide numbers are useful, but today’s results are highly dependent on the specific city, neighborhood, property type, and competition surrounding an individual home.
If you own a rental property in the Phoenix Metro, Home Ladder Property Management can provide a free rental analysis to help determine how your property compares with today’s market.